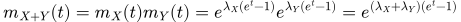Poisson Distribution
The Poisson distribution is a probability mass function.
Contents
Description
For a fixed number of independent trials, the number of successes is described by the binomial distribution. The probability of a success is denoted p in this case.
Instead of a fixed number of trials in some span of time, consider dividing the span of time into variable n intervals of size 1/n. The expected number of successes is denoted λ, so the probability of success in one interval is λ/n. As an example, if λ is the expected number of successes per day and n = 24, then λ/n is the probability of success in one hour.
It follows that, for a given n, the probability of 0 ≤ k ≤ n successes is given by a binomial distribution.

Take the limit of this distribution as n goes to infinity to arrive at the Poisson distribution. (This inherently means that p approaches zero as well.)

The distribution describes the probability of k event successes.

Moments
The expected value is given as E[X] = λ.
The moment generating function of the Poisson distribution is:
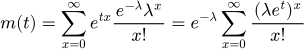
This is now a standard power series that will always converge.
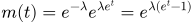
It follows that the expected value is λ.

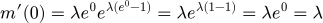
Variance is given as Var[X] = λ.
Usage
Poisson Approximation
A binomial distribution with a small p can be approximated by the Poisson distribution with λ = np. This is mostly only useful for extremely large n such that computation of the factorial (for the binomial coefficient) would be computationally prohibitive.
Sum of Poisson Variables
The sum of multiple Poisson distributed random variables is also a Poisson variable.
If Y = X1 + ... + Xk where Xi ~ Poisson(λi) for all i, then Y ~ Poisson(λ1 + ... + λk).
This can be proven using the moment generating function. Consider the simplest case of the sum of two variables: