
|
⇤ ← Revision 1 as of 2026-09-15 19:11:04
Size: 1355
Comment: Initial commit
|
← Revision 2 as of 2026-09-16 14:14:25 ⇥
Size: 1665
Comment: Notes
|
| Deletions are marked like this. | Additions are marked like this. |
| Line 33: | Line 33: |
| The domain of the moment generating function ''m(t)'' is the set defined by ''{t | m(t) < infty}''. |
|
| Line 36: | Line 38: |
| * The inversion theorem shows that if ''m,,X,,(t)'' is finite for all ''t ∈ [-a,a]'' for some ''0 < a'', and if ''m,,X,,(t) = ''m,,Y,,(t)'', then ''X'' and ''Y'' have identical distribution functions. |
Moment Generating Function
When a random variable's probability distribution function is used as a generating function, it is known as a moment generating function.
Description
For a given random variable X, the moment generating function may be notated mX.
The moment generating function derives from the Laplace transform of the probability distribution function for X:

Often it is written using a substitution t = -s, as:
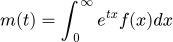
This is actually also valid for discrete random variables, in which case:

In the general form of the Laplace transform, s is treated as a complex valued constant, but in this application s (or t) will always be 0. Note that this also renders the sign meaningless (thus the reversed sign in the substitution is valid).
Properties
The domain of the moment generating function m(t) is the set defined by {t | m(t) < infty}.
Any Laplace transform of a function has a unique inverse that transforms back into the original function. This is to say:
- The probability density function can be recovered from the moment generating function.
- A distribution is uniquely identified by its moment generating function.
The inversion theorem shows that if mX(t) is finite for all t ∈ [-a,a] for some 0 < a, and if mX(t) = mY(t), then X and Y have identical distribution functions.